Two Free Ebooks for New Mexico Homeowners
Warm, practical, page-through ebooks written by Nysha Lynn Livingston. Home buyers can start with the First-Time Home Buyer's Guide, and homeowners planning their next move can read Buy Before You Sell. Read either one like a book, page by page.
by Nysha Lynn Livingston · REALTOR® · MORE Realty · Albuquerque, New Mexico
A hardcover you can actually open
Open the cover and turn real pages. On a desktop you get a two-page spread with the fold in the middle; on a phone the book fits your screen one page at a time. Tap, swipe, or use the arrows to move through all 14 pages.
Take the guide with you
Enter your name and email to unlock your copy of the full guide. Nysha follows up personally with every reader, and your information stays private.
Prefer to just read it here?
Use the arrows, tap the page edges, or swipe to turn pages.
What's Inside
Welcome: Why Albuquerque and Rio Rancho
Welcome. If you are reading this, you are thinking about buying a home in Albuquerque, Rio Rancho, or one of the surrounding New Mexico communities, and you are doing it at the right time to be prepared. This guide walks you through every step, from figuring out what you can afford to holding the keys in your hand. I wrote it the way I talk with my own buyers, in plain language, with real numbers and honest guidance.
A market with room to grow
The Albuquerque metro has quietly become one of the more attainable markets in the West. The median home price sits around $385,000, near the record reading of $387,500 set in July 2026, and it stays below the national median of roughly $440,600. Rio Rancho's three-month median is near $389,000. For many buyers, your dollar simply goes further here than it does in Denver, Phoenix, Salt Lake City, or Austin.
Why people move here
New Mexico offers more than 310 days of sunshine a year and a high-desert climate with four real seasons. The economy is anchored by Kirtland Air Force Base, Sandia National Laboratories, the University of New Mexico, and a growing healthcare and tech sector. The metro is big enough to offer everything you need, and small enough to feel welcoming.
A note on 2026
Prices are near record highs, supply is building, and mortgage rates are hovering near 7 percent. For buyers, that combination means more choices and more room to negotiate than in several seasons. The advantage in this market belongs to the prepared, which is exactly what this book helps you become.
"The buyers who win in this market are the ones who start with a plan. This book is your plan."
Is Homeownership Right for You Now
Before you look at a single listing, it is worth asking one honest question: is now the right time for you to buy? The answer has less to do with the market and more to do with your own situation. Homeownership is a decision about your life, not just your finances.
Signs homeownership may fit you
- You have a stable income you expect to keep for the next few years.
- You plan to stay in the area for several years, so buying makes financial sense.
- You are comfortable with the responsibility of maintenance and repairs.
- You want predictable housing costs and the chance to build equity over time.
Run the honest math
Compare what you pay in rent today with what a home would actually cost: principal, interest, taxes, insurance, HOA dues, utilities, and maintenance. Use a mortgage calculator to get a realistic picture before you decide.
There is no perfect moment
Waiting for perfect timing usually just means renting longer. Rates and prices will always move. What you can control is your own readiness: a solid credit profile, a down payment plan (even a small one works with the right help), and a clear picture of your monthly budget.
How Much House You Can Afford
Your budget is the foundation of the whole search. Knowing your number keeps you confident and keeps you from falling in love with a home you cannot comfortably carry.
The rule lenders actually use
Lenders generally keep your total housing payment, including principal, interest, taxes, and insurance (PITI), at or below about 28 percent of your gross monthly income. The practical version is simple: multiply your gross monthly income by 0.28, and that is roughly the monthly payment you can carry before other debts tighten it further.
What a median-priced home costs in 2026
On a $385,000 home with 10 percent down, the loan is about $346,500. At roughly 6.76 percent over 30 years (the average for the week ending September 10, 2026), principal and interest come to about $2,250 a month. Add modest New Mexico property taxes and homeowners insurance, and the total lands near $2,625 a month before any HOA fee. That works out to about $9,400 in gross monthly income, or roughly $112,000 to $113,000 a year. Approximate estimate for illustration; your exact payment depends on taxes, insurance, HOA dues, your credit, and your rate.
Every quarter point matters
A common rule of thumb: every quarter point of mortgage rate changes the payment by about $60 per $100,000 borrowed. Rates pushed toward a one-year high near 7 percent after the Federal Reserve raised rates on September 16, 2026. Ask your lender for a fresh quote, because a quote from even a week ago can already be stale.
Don't forget the rest
Budget for property taxes (roughly 0.8 to 1.4 percent depending on county), homeowners insurance, HOA fees in some communities, utilities in our desert climate, maintenance, and closing costs (typically 2 to 5 percent of the purchase price).
Down Payment and Assistance Programs in New Mexico
Here is the part that surprises most first-time buyers: you may not need as much cash as you think. New Mexico has genuinely strong help for qualified buyers, and too few people ask about it.
The down payment menu
- Conventional loans: as low as 3 percent down for qualified buyers.
- FHA loans: 3.5 percent down, a long-standing favorite for first-time buyers.
- VA loans: zero down for eligible veterans and active-duty buyers, with no mortgage insurance.
- USDA loans: zero down for qualifying rural and some suburban addresses.
New Mexico Mortgage Finance Authority (Housing New Mexico)
MFA runs the main state assistance programs through approved lenders. You generally complete homebuyer education and use an MFA-approved lender. Options include the FirstHome first mortgage, FirstDown down payment assistance (up to about $8,000 as a 0 percent, deferred second mortgage), FirstDown Plus, HomeNow with up to about $7,000 in deferred assistance, and the DownPaymentAdvantage grant of up to $25,000 for buyers at or below 80 percent of area median income.
How to use them
Program amounts and funding do change, so treat these as a starting point and verify current terms with an MFA-approved lender. The point for you is that a meaningful chunk of your upfront cash can come from programs you may never have heard of, and that often moves a borderline budget into the yes column.
Seller concessions can also reduce your cash-to-close, which we cover in Chapter 8.
Getting Pre-Approved: Working With Your Lender
A pre-approval turns you from a hopeful browser into a serious buyer. It tells you exactly what you can borrow, shows sellers you are ready, and sets your search on solid ground.
Pre-approval versus pre-qualification
A pre-qualification is a quick estimate. A pre-approval means a lender has reviewed your documents and is prepared to lend you a specific amount. Sellers and listing agents want to see the letter, especially in a market where multiple offers are common.
What to bring
Plan to provide two years of tax returns and W-2s, recent pay stubs, bank statements, and documentation of any other income, assets, or debts. Be ready to explain large deposits. The more complete your file, the smoother the process.
Choosing a lender
A local lender who knows New Mexico programs (VA, FHA, USDA, and MFA assistance) is a real advantage. Rates vary between lenders, so compare Loan Estimates and ask questions. Nysha can connect you with trusted local lenders who specialize in first-time buyer programs.
Rates in 2026
The 30-year fixed averaged about 6.76 percent for the week ending September 10, 2026, and moved toward a one-year high near 7 percent after the Fed's September 16 hike. Ask for current pricing when you are ready to make an offer, and consider locking a rate once you find your home.
Protect your credit
Check your credit reports early, pay down balances, and avoid opening new credit or making large purchases between pre-approval and closing. Anything that changes your debt or credit can change your loan.
Choosing the Right Area
The right area for you is the one that fits your practical priorities. This chapter gives you an objective framework for comparing areas. One principle runs through all of it: everyone has the right to live in any community they choose, and a professional agent serves all buyers equally and fairly.
Start with practical priorities
Make a list before you tour: commute time to work, price range, home type (single-family, townhome, condo, or new construction), lot size, whether you want an HOA, and access to transit and everyday services. These concrete factors make areas easy to compare side by side.
Schools, verified directly
If schools matter to you, check the exact attendance zones with the school district and visit schools yourself. School information changes and is best confirmed with the district, not with a neighbor's guess.
Utilities and services
Most of the metro is served by municipal water and sewer. Some rural-edge communities use private wells and septic systems, which have their own inspections and long-term costs. Ask about what a given area uses before you fall in love with a property.
Do your own drive-throughs
Visit areas at different times of day, test your commute, walk the neighborhood, and talk to residents. Your own experience is the best guide to whether a place fits your day-to-day life.
Fair Housing
Federal and New Mexico law protect your right to housing free from discrimination based on race, color, religion, national origin, sex, disability, or familial status. As a REALTOR, I serve every client equally and will help you find a home that fits your needs and budget, wherever that may be. Your choices are yours to make, and I am here to guide you fairly and professionally.
The Home Search
Now the fun part: finding your home. A focused search saves you time, and knowing what you are looking at keeps you from getting swept away by a pretty kitchen.
Set your criteria and stick to them
Separate must-haves from nice-to-haves, and share them with Nysha. She sets up a custom MLS search that sends you new listings the moment they hit the market, so nothing good slips by.
What to notice when you tour
Look past the staging at the things that cost money: the age and condition of the roof, the HVAC and any swamp cooler, the water heater, the foundation, plumbing and drainage, and the windows. New Mexico homes often bring adobe or stucco walls, flat or low-slope roofs, and swamp coolers, all of which deserve careful attention. Older clay or cast-iron sewer lines are common in established neighborhoods and can be costly to replace if overlooked.
The 2026 market in one glance
The metro median is near $385,000, homes average about 34 days on market, and the list-to-sale ratio is near 97 percent. Active supply has climbed to about 3,850 listings, with months of supply around 3.9 across all property types and leaner near 2.3 months for detached homes. In plain terms: more choices and more room to negotiate than buyers have seen in years.
New construction as a path
With resale supply still tight, new construction in Rio Rancho and across the metro is a reliable way to find a home without a bidding war. As a Certified New Home Specialist (CNHS), Nysha helps buyers navigate builder contracts, upgrades, and warranties.
Making an Offer and Negotiating
When you find the right home, your offer is your first impression. A well-put-together offer backed by real market data gets the conversation started on your side.
Know the comps
Comparable sales, days on market, and the list-to-sale ratio tell you how to price an offer. With the list-to-sale ratio near 97 percent, sellers are closing close to asking, so an offer built on recent comparables is your strongest position.
The pieces of an offer
An offer includes the price, earnest money, financing terms, contingencies (financing, inspection, and appraisal), a proposed closing date, and any requested seller concessions. Each piece affects how the seller reads your offer.
Seller concessions can change the deal
A seller contributing toward your closing costs or buying down your rate can reduce both your cash-to-close and your monthly payment. These have become more common in 2026 as the market rebalances, so it is always worth asking.
Negotiation, handled for you
As a Master Certified Negotiation Expert (MCNE), Nysha handles counteroffers, timelines, and inspection requests with your interests first. Every transaction is different, and her job is to protect you while keeping the deal moving toward the closing table.
Inspections, Appraisal, and Closing
This is where the deal becomes a home. There is paperwork, there are professionals, and there is a clear path to closing day.
The home inspection matters
A professional inspection is one of the most important steps. New Mexico homes come with unique considerations: adobe and stucco construction, flat and low-slope roofs, swamp coolers, aging sewer lines, and, on the rural edges, private wells and septic systems. Read the report carefully, ask questions, and prioritize what matters.
What happens after the inspection
Based on what the inspector finds, you may negotiate repairs or a credit with the seller. Tackle safety and structural items first, and treat cosmetic issues as what they are.
The appraisal
Your lender orders an independent appraisal to confirm the home's value matches the purchase price. If it comes in below your offer, we work through the options together.
Closing day
The title company coordinates the final steps. You review the Closing Disclosure line by line, sign the documents, and pay your remaining down payment and closing costs, typically 2 to 5 percent of the purchase price. From accepted offer to closing, the usual timeline is about 45 to 60 days.
Keys in Hand: Moving In and Beyond
The keys are yours. Congratulations. Buying your first home is a big deal, and you did the work to make it happen the right way.
The first week
- Change your address with the post office and update your ID and registration.
- Set up utilities: electric, gas, water, trash, and internet.
- Re-key or change the locks and program any garage or security systems.
Make it official
Keep your closing documents in a safe place, set up automatic payments or reminders for your mortgage and property taxes, and update your homeowners insurance with your new address.
A home is a project, not a problem
Budget for maintenance and handle small issues early, because small issues are cheaper than big ones. In a desert climate, seasonal care for your roof, cooling, and landscaping keeps your home comfortable year-round.
Taxes you may qualify for
New Mexico offers property tax savings that can lower your bill, including the Head of Family exemption and a senior valuation freeze. Ask what applies to your situation.
You are never done learning
Home values, rates, and your own needs will change over time. When it is time for your next move, you will know exactly how the process works, and Nysha will be here when you need her.
About Nysha Lynn Livingston
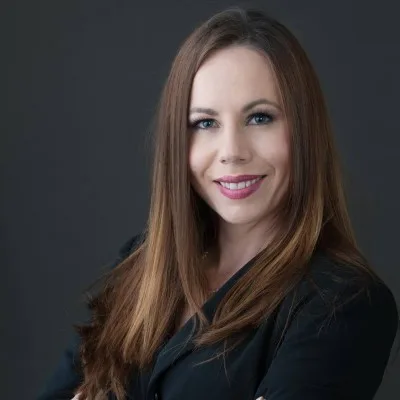
Nysha Lynn Livingston is a trusted, top-performing REALTOR at MORE Realty in Corrales, New Mexico, with 12+ years of experience and 180+ homes sold. She holds advanced designations including Accredited Buyer's Representative (ABR), Certified New Home Specialist (CNHS), Master Certified Negotiation Expert (MCNE), Certified Residential Specialist (CRS), and more, and is licensed in New Mexico (License #48827).
She serves Albuquerque, Rio Rancho, Corrales, Placitas, Los Ranchos de Albuquerque, North Albuquerque Acres, High Desert, Glenwood Hills, Sandia Heights, Four Hills, and Volterra. Whether you are buying, selling, or investing, Nysha brings deep local knowledge, skilled negotiation, and genuine care to every transaction.
This ebook is the same guidance she gives her own buyers, written down so you can work through it at your own pace.
Ready to Make Your Move?
You now have the full picture of the home buying process. The next step is simple: turn this guide into a personalized plan. Book a free consultation with Nysha, and she will help you run your real numbers, connect you with a trusted lender, and start your search with clarity.
No pressure, no obligation. Just a friendly, experienced conversation about your goals.
Thanks for Reading
Thank you for reading through the whole guide. This ebook is the same advice Nysha gives her own buyers, now in a form you can work through at your own pace, page by page.
When you are ready for the next step, reach out for a free, no-pressure conversation about your goals. Nysha answers every message personally.
Take the Guide With You
Enter your name and email and Nysha will send you the downloadable PDF version of this guide, so you can keep every chapter on your phone, tablet, or desktop.
Download the PDFNysha follows up within one day.
Your information stays private and is never shared.
Equal Housing Opportunity. Nysha serves all buyers and sellers equally and fairly, in every community.
Unlock the rest of the book
You are past the sample pages. Enter your first name and email to unlock the remaining chapters, and Nysha follows up within one day.
Nysha personally follows up within one day.
Your information stays private and is never shared.
Fair Housing: Nysha Lynn Livingston and MORE Realty provide equal professional service to all persons regardless of race, color, religion, national origin, sex, disability, or familial status. Equal Housing Opportunity.
Buy Before You Sell: A Homeowner's Guide to Buying Your Next Home First
For homeowners in Albuquerque, Rio Rancho, and the surrounding New Mexico communities: a practical, page-through guide to buying your next home before you sell your current one, from financing the overlap to planning two closings.
by Nysha Lynn Livingston · REALTOR® · MORE Realty
Take the guide with you
Enter your name and email to unlock your copy of the full guide. Nysha follows up personally with every reader, and your information stays private.
Prefer to just read it here?
Use the arrows, tap the page edges, or swipe to turn pages.
What's Inside
Why Buy First, Then Sell
Welcome. If you own a home and are thinking about your next one, you have probably asked yourself the same question: should I sell my current home first, or find my next home first? Many homeowners in Albuquerque, Rio Rancho, and the surrounding New Mexico communities are choosing to buy first and sell after. This guide explains how that works, when it makes sense, and how to handle the months when you may own two homes at once.
Why homeowners buy first
- They can take their time finding the right home instead of settling under a deadline.
- They do not have to coordinate their offer with the timing of their own sale.
- They can move straight from one home to the next and avoid a temporary move or a storage unit.
- They keep control of their timeline, including the option to negotiate a rent-back if it helps.
What this guide covers
The chapters that follow walk through the strategy, budgeting with two properties, financing options such as bridge loans and home equity lines of credit, contingent offers, timing, prepping your current home, and the logistics of two closings. It is general guidance, not legal, tax, or financial advice. Your lender and your real estate and tax professionals turn this into a plan for your situation.
"Buying first can feel like a big step. Done with a clear plan, it is simply the next step."
Welcome: Why Buy First, Then Sell
The buy-before-sell strategy is simple to describe: you make an offer on your next home and close on it before your current home sells. The appeal is equally simple. You never have to make a move under pressure, and you are ready to act the moment the right home appears.
When it makes sense
- You have enough equity and income to qualify for and carry both homes for a time.
- You can cover the down payment and closing costs without relying on the sale of your current home.
- The supply of homes you want is limited, so being ready to move quickly matters.
- You have flexibility in your timeline and can absorb an unexpected delay.
When it may not be the right fit
- You plan to use the proceeds of your current sale for the down payment on the next home.
- Carrying two sets of housing costs would stretch your monthly budget too thin.
- You have limited equity, or your lender cannot qualify you with both payments in the picture.
- You prefer the certainty of selling first and moving once into a settled budget.
The honest middle path
Many homeowners land somewhere in between. They get their finances ready, prepare their current home to sell, and stay flexible about which side closes first. The goal is a plan you can live with comfortably, and the numbers, not just the wish list, should drive that decision.
The Buy-Before-Sell Strategy
When you buy before you sell, your budget suddenly covers two homes: the one you are moving into and the one you still own. The good news is that this is a math problem, not a mystery. Lay both sets of costs out side by side and the plan becomes clear.
Know every cost of both homes
- Your next home: principal, interest, taxes, insurance, any HOA dues, utilities, and maintenance.
- Your current home: the same list, plus the cost of keeping it show-ready while it is listed.
How lenders look at two mortgages
During the overlap you may carry two mortgage payments, and lenders generally count both against your debt-to-income ratio. That is why financing the overlap is usually arranged before you shop: a pre-approval that reflects the carrying plan gives you a realistic number to work with.
Build a carrying-cost worksheet
- Write down the monthly cost of your current home.
- Estimate how many months you may carry both homes.
- Multiply the two to get your total carry cost.
- Add a buffer of several months in case the sale takes longer than planned.
Concrete numbers are the best protection against a plan that looks fine on paper and feels heavy in practice. If the two-home budget is tight, that is a signal to adjust the plan, not to ignore it.
Budgeting with Two Properties
Financing the gap between buying and selling comes down to a handful of familiar tools. Each one uses the equity in your current home, and each has its own costs, timelines, and trade-offs to review with your lender.
Bridge loans
A bridge loan is short-term financing secured by your current home. You borrow against the equity you expect to receive when it sells, and the loan is typically repaid from the sale proceeds. Bridge loans are designed for exactly this situation: buying the next home before the current one closes.
Home equity line of credit (HELOC)
A HELOC is a revolving line of credit backed by your home's equity. You draw what you need, when you need it, and you pay interest only on the amount you use. It can fund a down payment, cover the months of overlap, or both, and it can stay in place after the move if you choose.
Home equity loans and cash-out refinancing
A home equity loan gives you a lump sum with fixed payments, and a cash-out refinance replaces your existing mortgage with a larger one. Both deserve a place in the conversation, and a lender can model which fits your equity, income, and timeline best.
There is no single right answer
The best choice depends on how much equity you have, how fast you expect your current home to sell, and what you are comfortable paying each month. Ask each lender to explain the costs, the rates, and what happens if the sale takes longer than expected.
Financing Options: Bridge Loans and Home Equity
A contingent offer says you will buy only once your current home sells. It protects you, and sellers read it as risk, so it is worth understanding exactly how your offer will be received.
What counts as a contingency
The most common sale contingency states that the contract depends on the successful closing of your current home. If your home does not sell, you can typically step away without penalty. That protection is valuable to you, and it is the uncertainty a seller takes on.
How sellers view them
Sellers generally prefer offers with the fewest conditions, especially when multiple buyers are interested. A contingent offer can be a deal-breaker for a seller on a tight timeline, and business-as-usual for another. Context matters, including how your agent reads the situation.
Ways to strengthen a contingent offer
- Line up your financing first, so the only open end is your own sale.
- Make the contingency window clear and short, with a defined backup plan.
- Show that your current home is already marketed and priced to move.
- Offer a flexible closing date or rent-back where it helps.
Ask your agent for an honest read on how contingent offers are received in the area where you are buying. Sometimes a bridge loan or HELOC removes the contingency entirely, which is why Chapter 3 matters.
Contingent Offers and How Sellers See Them
Your current home's equity is usually the strongest asset in a buy-first plan. Equity is simply what your home is worth minus what you owe on it, and it can fund your next move before your current sale closes.
Accessing equity before you sell
Bridge loans, HELOCs, home equity loans, and cash-out refinancing all let you turn equity into cash or credit early. Lenders weigh your equity, income, and credit, so the amount you can access is specific to your situation. Together with your lender, you can decide how much of that equity to tap and when.
The new home construction angle
New homes are built to a schedule, often months from contract to completion. That timing can work in your favor. You may be able to sell your current home while the new one is being built, then move in at completion. Plan for the build timeline, your carry costs if the new home finishes before your current home sells, and any builder deadlines or deposit terms in the contract. As a Certified New Home Specialist, Nysha helps buyers understand builder contracts, timelines, and warranties.
Keep the final settlement in mind
When your current home sells, the lender with a lien on it is paid from the proceeds, and any remaining equity comes to you. Knowing that order of payments helps you see why the lender wants your financing approved before you shop, and why the paperwork on both sides needs to line up.
Using Your Equity, Including New Construction
The heart of the buy-first plan is the overlap: the time between closing on your new home and closing on your current one. Planning for it well is the difference between a smooth move and a stressful one.
How long the overlap can last
The overlap is as short as you make it. Some homeowners close on both homes within days or weeks. Others carry both for months, often by choice, to allow time for repairs, market conditions, or a new-build timeline. Your plan sets the length, and your lender and agent help you estimate what is realistic in your market.
Plan for the cost of carrying both
- Total your current home's monthly costs, including mortgage, taxes, insurance, and utilities.
- Multiply by the number of months you expect to carry both homes.
- Add a cushion for the sale taking longer than expected.
- Keep that number visible while you shop, so the plan stays grounded.
Levers that shorten or lengthen the overlap
A rent-back agreement lets you sell first and stay in your home as a tenant, which can shorten the overlap to nearly zero. Choosing an earlier or later closing date on either side gives you control over the exact length. And a well-priced, well-presented home tends to sell within its market's typical timeframe, so ask your agent for their experience with listing timelines in your area.
Timing and Carrying Both Homes
Shopping for a new home and selling your current one at the same time is a full plate. The homeowners who handle it best start their prep early and keep both processes moving on separate tracks.
Start with the fast wins
- Declutter room by room, and pack what you will not need before the move.
- Handle the small repairs that show up in listing photos, like touch-up paint and easy fixtures.
- Deep-clean, and consider staging to help buyers picture the space.
- Gather documents early: disclosures, warranties, receipts for improvements, and HOA paperwork.
Keep it show-ready while you shop
A buyer can request a showing at short notice. A quick tidy-up routine, a flexible schedule, and a plan for pets make showings easy instead of stressful. Your agent can batch showings and set a schedule that works for you.
Pace yourself
Two processes at once is a lot, even when both are going well. Use checklists, lean on your agent and lender for reminders, and protect your evenings and weekends where you can. You are doing the work now so the move itself is calm.
Prepping Your Current Home While You Shop
The final stretch is the least glamorous and most satisfying part: two closings, one move, and a new front door. A little coordination goes a long way.
Choose your sequence
Most buy-first movers close on the new home first and the old home soon after. How far apart the closings fall is your plan to set: days give you a short overlap, and weeks give you room to move at your own pace.
Overlapping closings, coordinated
When two closings overlap, the title companies and lenders on each side need to know the other exists. Share your target dates early, confirm each side can hit them, and build in a few days of cushion in case one closing slips. Your agents can coordinate the details so neither side is surprised.
Plan the move itself
- Book movers early, and confirm the dates once both closings are scheduled.
- Pack in stages, and label boxes by room and priority.
- Arrange utilities: transfers on the new home, and scheduled disconnects on the old one.
- Update your address for mail, registrations, and services before the closing date.
When the closings sit close together, a few days of overlap time is your buffer for the unexpected, so aim for a schedule with room to breathe.
Making a Smooth Move with Two Closings
Most buy-first headaches are preventable. Here are the common ones to watch for, followed by an action checklist you can work through with your agent and lender.
Common mistakes
- Underestimating how long the overlap can last, and how much it costs each month.
- Starting the shopping without a clear financing plan for carrying both homes.
- Waiting until the last minute to prepare your current home for the market.
- Ignoring how contingent offers are received, and missing the chance to strengthen yours.
- Leaving closing dates uncoordinated, so the move lands in a hard spot.
- Spending the equity cushion before the plan is fully funded.
Your action checklist
- Meet with a lender and model the cost of carrying both homes.
- Get pre-approved with the carrying plan reflected in your numbers.
- Choose your financing approach: bridge loan, HELOC, home equity loan, or another fit.
- Interview agents and list your current home once it is ready.
- Prep, stage, and photograph your current home while you shop.
- Set your target overlap and closing dates with both agents.
- Coordinate title companies, lenders, and movers as the dates firm up.
- Keep your cushion intact and revisit it as the market moves.
Each step is small. Together they make buy-first feel less like a gamble and more like a plan.
About Nysha Lynn Livingston
Nysha Lynn Livingston is a trusted, top-performing REALTOR at MORE Realty in Corrales, New Mexico, with 12+ years of experience and 180+ homes sold. She holds advanced designations including Accredited Buyer's Representative (ABR), Certified Residential Specialist (CRS), Master Certified Negotiation Expert (MCNE), Certified New Home Specialist (CNHS), and more, and is licensed in New Mexico (License #48827).
She serves Albuquerque, Rio Rancho, Corrales, Placitas, Los Ranchos de Albuquerque, North Albuquerque Acres, High Desert, Glenwood Hills, Sandia Heights, Four Hills, and Volterra. Whether you are buying, selling, or both, Nysha brings deep local knowledge, skilled negotiation, and genuine care to every transaction.
This ebook is the same guidance she gives her own homeowner clients, written down so you can work through it at your own pace.
Ready to Plan Your Move?
You now have the full picture of the buy-first strategy. The next step is simple: turn this guide into a personalized plan. Book a free consultation with Nysha, and she will help you run your real numbers, connect you with a trusted lender, and map out the timeline for both homes.
No pressure, no obligation. Just a friendly, experienced conversation about your goals.
Thanks for Reading
Thank you for reading through the whole guide. Buying your next home before you sell your current one is a strategy with real advantages, and it works best as a plan: financing arranged, numbers written down, and both timelines coordinated.
When you are ready for the next step, reach out for a free, no-pressure conversation about your goals. Nysha answers every message personally.
Take the Guide With You
Enter your name and email and Nysha will email you the downloadable PDF version of this guide, so you can keep every chapter on your phone, tablet, or desktop.
Nysha follows up within one day.
Your information stays private and is never shared.
Equal Housing Opportunity. Nysha serves all buyers and sellers equally and fairly, in every community.
Unlock the rest of the book
You are past the sample pages. Enter your first name and email to unlock the remaining chapters, and Nysha follows up within one day.
Nysha personally follows up within one day.
Your information stays private and is never shared.
Fair Housing: Nysha Lynn Livingston and MORE Realty provide equal professional service to all persons regardless of race, color, religion, national origin, sex, disability, or familial status. Equal Housing Opportunity.